I recently found myself "retiring" two years ahead of plan at 50. I watched my grandfather work crazy hours at the expense of his family as a CFO and Controller of a public company only to see him be handed a gold watch upon retirement. My dad also watched that unfold; he retired at 52 and never looked back - that was over 20 years ago.
As such, I always knew that I wanted to "retire" as soon as I could be comfortable. There is no reason to work until you die. Like me, you probably have had friends die that were going to retire after "just one more year" or die soon after retirement.
Source: Azerbaijan
Which Stocks Might Be Part of a Retirement Portfolio?
There is a lot to be said for building a portfolio of stocks for the long haul. As you get older, your time horizon is reduced and would tend that one should allocate more to lower beta stocks and "safer" investments that pay dividends. Stocks like the following should be reviewed as part of a portfolio: Johnson & Johnson (NYSE:JNJ), Medtronic (NYSE: MDT), Coca-Cola (NYSE:KO), Colgate-Palmolive (NYSE:CL), Procter & Gamble (NYSE:PG), 3M (NYSE:MMM), Lowe"s (NYSE:LOW), as well as stocks in the Internet of Things (IoT) space.
Source: news.com
Johnson & Johnson
Source: jnj.com
Taking a deeper dive into one of these companies, let"s look at JNJ. JNJ is a large conglomerate positioned for the future. As America continues to age, JNJ can assist more retiree with health challenges. An older population should equate to growing profits for JNJ.
In JNJ"s 4Q2017 earnings call, it was mentioned that healthcare is a monumental part of each and every one of our lives. It accounts for 18% of U.S. GDP. Pharmaceutical spending accounts for about 14% of the overall healthcare spending in the U.S.
In addition to JNJ being named a 2018 Fortune World"s Most Admired Company, they are one of the most respected and well-managed companies. JNJ"s dividend has increased 55 years in a row.
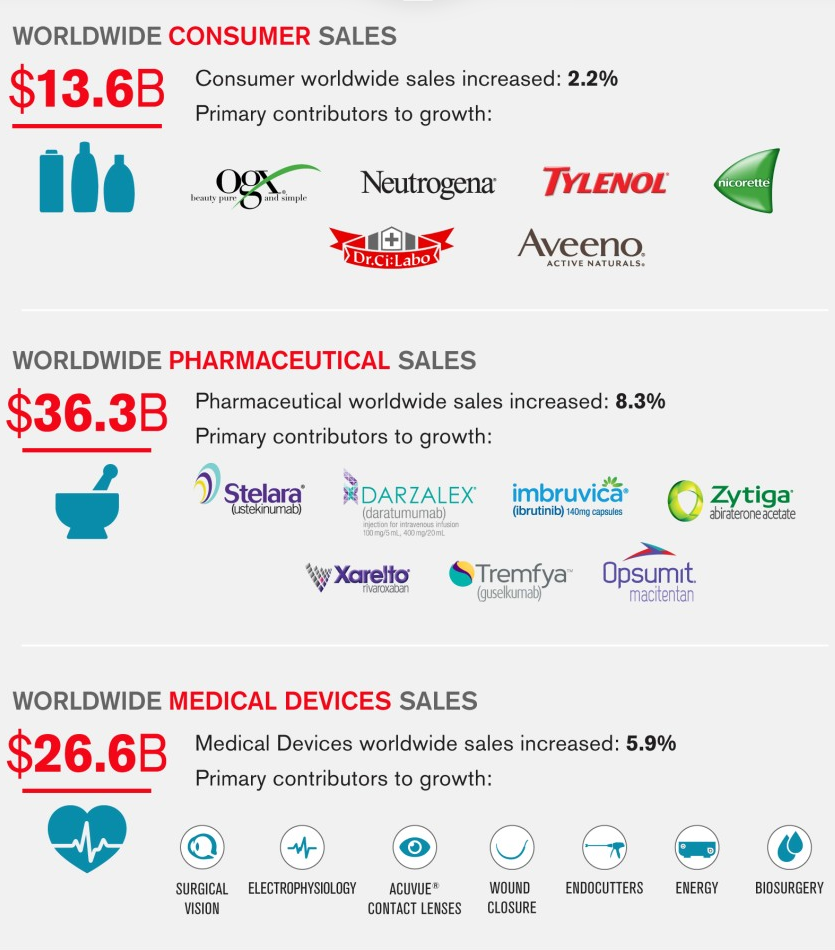
In their latest earnings release, JNJ announced $76.5 billion in sales in 2017, with growth reported in all three sectors: Consumer, Medical Devices and Pharmaceuticals, the latter of which reported a worldwide sales increase of 8.3%.
Source: Johnson & Johnson Homepage | Johnson & Johnson
Pipeline
For 2018, they expect growth to come from expanding key life-saving and life-changing products, such as DARZALEX (for multiple myeloma therapy), IMBRUVICA (to slow or stop the growth of some types of cancer cells) and STELARA (for treating Crohn"s Disease).
Technical & Fundamental Analysis
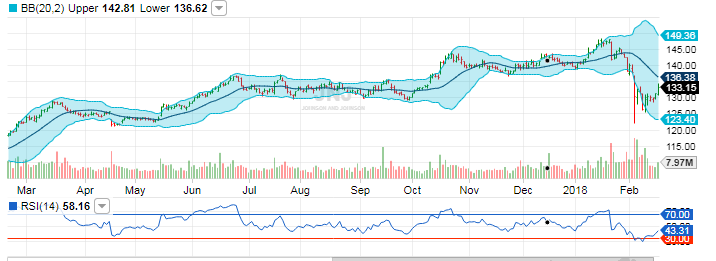
A key support was pierced and the stock is trading below its 20-day and 50-day moving averages of 137.09 and 140.08, respectively. The RSI is below 50 but oversold. There appears to be some risk of downside to the 121 range. Resistance is approximately at 136. Alternatively, if resistance is broken, look for targets in the 143 to 146 range.
The stock is yielding 2.56% - this will not get most dividend investors excited. However, as mentioned above, with a 55 year dividend payment track record, it would appear stable and consistent.
Source: fidelity.com
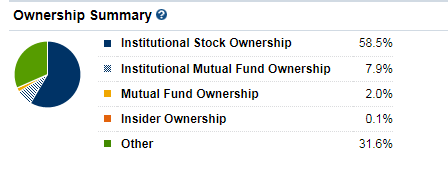
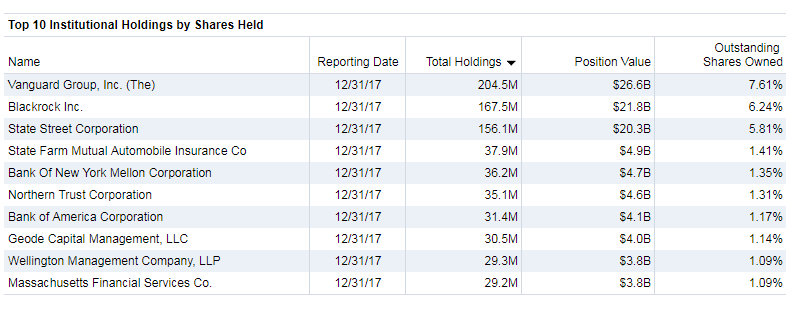
The stock is also widely held which should give the individual investor some assurance of owning this stock for the long term.
Source: eresearch.fidelity.com
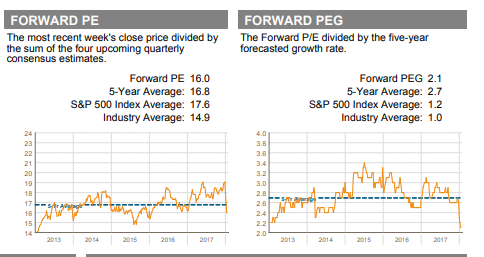
JNJ"s forward P/E is 16 which is approximately at 5% discount to its 5-year average of 16.8. In addition, its forward PEG of 2.1 is currently at the low end of the 5-year range. In addition, with almost $42 billion in cash overseas (representing 98.6% of total cash and marketable securities), JNJ could reduce their debt position if this cash was repatriated to the US.
Source: Thomson Reuters Stock Reports
JNJ Summary
While downside risk is possible, with a forward P/E of 16, the current price for JNJ might be an attractive entry point for investors. JNJ appears to be a company with high quality earnings and consistent dividend. Overall, for the long term, JNJ appears to be a buy for someone seeking strong and stable dividend growth.
How Much Money Do You Need?
Circling back to the original question of how much money do you need to retire - the problem is for most of us, but especially me, is that I"m driven by fear and greed far too often. That goes for investing and living. While made popular by various movies and the media, those emotions are not what life is about.
There must be a way to be frugal and retire from the rat race and to be able to rewire yourself to follow your desires, work for yourself, give back to the community. But how? With over 30 years of investing and saving, I have a number of strategies to share below and in future articles.
The big question is "how much do I need to retire"? It really depends two main things: how long will you live and how much you will spend, net of earnings.
According to a report from the Economic Policy Institute (EPI), the mean retirement savings of all working-age families, which the EPI defines as those between 32 and 61 years old, is $95,776.
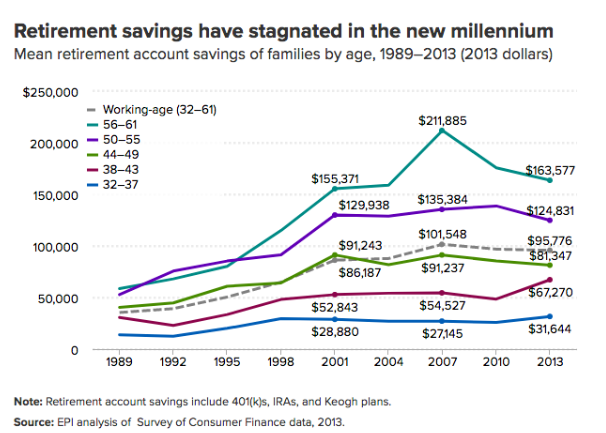
It appears from the above that most of us will not retire with a seven-figure portfolio. Will most people keep working forever? Is there a way to save more for retirement?
Guidelines & Portfolios
As mentioned above, how can you know if you are spending at the right level? There are a number of "rules of thumb". One is the four percent rule is a rule of thumb used to determine the amount of funds to withdraw from a retirement account each year. This rule seeks to provide a steady stream of funds to the retiree, while also keeping an account balance that allows funds to be withdrawn for a number of years. Simply put, if you plan on spending $50,000 a year in retirement, you will need (according to this rule) $1,250,000 (50,000/.04). More on the advantages and disadvantages of this in a future article.
One might also consider a bond fund or bond laddering. There are a number of good resources for developing a portfolio of bonds to provide you with the income that you need in retirement. I personally like what Fidelity Investments offers in this space. In short laddering seeks to avoid reinvestment risk by not reinvesting a large portion of assets in an unfavorable interest rate environment. Each "rung" of the ladder represents a specific bond with a specific maturity rate and yield.
Get Ready for Retirement
Source: MCERA
There are a few basics for those not quite at retirement:
- Remember the value of compounding - save as much as you can as early as you can.
- Always spend less than you make (some of my mom"s best advice)
- If you use credit cards, pay them off every month. No exceptions.
- Make sure your investments work hard for you.
- Put as much as you can into investments automatically each month.
In retirement, there are a number of lifestyle changes that you might be able to make, but they take more effort:
- Budget. We budgeted for the first several years of our marriage. We started to budget again when we retired. Determine what your expenses are - what"s fixed, what"s variable and adjust accordingly.
- Income Strategy. In conjunction with creating a budget, you will need to determine what your income will be and where your spending money will come from. When you enter retirement, your spending money will come from various sources instead of a paycheck. Part time job, social security, pension, investment income are all potential sources. More on this in the next section below.
- Downsize. We have lived in big houses and small houses. There are several advantages to live in a small house. It"s less costly to heat and cool. Taxes are most likely less. It is easier to maintain. The catch - let"s get real here - it might not be something that people will drive by and envy. Isn"t that why most of us live in a big house - to show others how successful we are?
- Pick the best state. More on this later, but where you retire makes a big difference in cost and enjoyment
- Medical. This is one of the biggest expenses and you really need health insurance. Unfortunately, good insurance is expensive. Shop around. Analyze the risk of over and under insuring. Use generic prescriptions whenever possible.
- Walk. We all need the exercise, so walk rather than driving. It will save gas.
- Fewer cars. Do you need two or more cars in retirement? If not, sell one. Cut your insurance and maintenance costs in half.
- Keep that car. Keep that car longer. Who are you trying to impress with a new, expensive car every couple of years?
- Clothes. Have nice looking clothes, but don"t go overboard. You are not going to the office anymore. Shop secondhand.
- Communication. Apparently everyone else stopped landline phone service years ago. Cut it. Shop for the mobile phone plan that you need and keep those phones longer.
- Travel. With visiting over 85 countries in my life, I"m all for traveling as much as possible. There are ways to see the same things everyone else does for a fraction of the costs - shop airline specials, book hotels that are safe and clean but not expensive. Why pay top dollar for a fancy reception counter and a pool. If you vacation right, you won"t be spending much time at the hotel anyway.
- Food. Eat at home more and cut back on eating out. Drink less booze. If you smoke, stop. It"s better for your heath and wallet.
- Shop. Shop around for the best prices. Buy what you need. Determine what is a need vs. a want.
Additional Disclosure
Thank you for your time in reading the above article. I read and write on a wide range of companies on a regular basis. If you would like to stay informed with articles like these, please click the "Follow" button at the top of this report and select "Get email alerts." If you have additional insights on the topic or contrasting views, please kindly share them in the comments section.
This article is intended to provide educational information to readers and in no way constitutes investment advice. Investing in public securities is speculative and involves risk, including possible loss of principal. The reader of this article must determine whether any investments mentioned in this article are suitable for their portfolio, risk tolerance and accept responsibility for their decisions. Neither information nor any opinion expressed in this article constitutes a solicitation, an offer or a recommendation to buy, sell, or dispose of any investment or to provide any investment advice or service. An opinion in this article can change at any time without notice.
Disclosure: I/we have no positions in any stocks mentioned, and no plans to initiate any positions within the next 72 hours.
I wrote this article myself, and it expresses my own opinions. I am not receiving compensation for it (other than from Seeking Alpha). I have no business relationship with any company whose stock is mentioned in this article.

No comments:
Post a Comment